Oct 26, 2026
Tackling Long-Term Care Questions
Most retirement planning conversations start in a familiar place. Am I on track? How much can I draw from my portfolio each year? How should I be invested?

Most retirement planning conversations start in a familiar place. Am I on track? How much can I draw from my portfolio each year? How should I be invested?
Those are the right questions. Another question belongs alongside them, and it tends to get pushed to the back of the list: what happens if one of us needs long-term care?
This isn't a scare tactic. It's a risk that applies to nearly everyone we meet. Industry research suggests roughly 7 out of 10 people will require some form of long-term care in their lifetime.
Here is a quick look at when to ask questions, what care costs, and how to fund it.
When Should You Have Conversations About Long-Term Care?
Your 50s and early 60s are often the sweet spot for a few practical reasons. Health still qualifies you. Most long-term care funding options involve some form of medical underwriting. A clean health history in your mid-50s opens doors that a knee replacement and a blood pressure prescription can start to narrow. The cost can also be lower. The earlier you put a policy in place, the longer you spread the premium and the less you generally pay over its life.
You still have earning years. Whatever solution you choose, funding it is easier while income is at its peak than after it stops. Choices made in a crisis are rarely the ones people would have made with time to think.
There's also a reason this lands differently in your 50s than it did in your 40s: a lot of people this age are watching a parent go through it right now. The question stops being theoretical.
What Long-Term Care Can Cost
Long-term care isn't one thing, and it isn't automatically a nursing home. Here's the range, with Pennsylvania figures from the most recent CareScout Cost of Care Survey.
Care at home. Help with bathing, dressing, meals, medication, and mobility at home. This is where most people start and where most people want to stay. In-home care in Pennsylvania averages roughly $6,483 per month for about 44 hours a week, or around $34 an hour. The math is worth understanding: a few hours a day is manageable, but continuous home coverage costs more than a facility.
Adult day services. Structured daytime programs with activities, meals, and health monitoring. Among the most affordable options available, and often the one families don't know exists. Its real value is giving a spouse providing care at home a genuine break.
Personal care homes and assisted living residences. A local distinction: Pennsylvania licenses two separate categories, Personal Care Homes and Assisted Living Residences, the latter created in 2010 with stricter staffing and aging-in-place requirements. Families tour both and often assume they're the same. Pennsylvania's assisted living median runs about $6,480 per month, slightly above the national median of $6,200.
Memory care. A secured setting with dementia-trained staff. Typically runs 20% to 30% above assisted living in the same market.
Skilled nursing. Round-the-clock medical care, and the most expensive setting on this list. Pennsylvania's median is roughly $11,954 per month for a semi-private room and $13,688 for a private room, which puts the state well above the national median.
Continuing care retirement communities. Pennsylvania has an unusually high concentration of these. You move in while still independent and transition through higher levels of care on the same campus. The financial structure differs from everything above, generally involving a significant entrance fee plus ongoing monthly costs, with contract types that vary widely in how much future care they actually cover.
Two Primary Ways People Fund Long-Term Care
Savings and investments. Self-funding sounds simple and isn't. The first test is whether you have enough accumulated to cover care while still supporting a surviving spouse and the goals you've set for the rest of your lives, and then some. The cost of care is genuinely unpredictable; no one can name that number with precision.
The second test matters more. Self-funding requires real tolerance for risk, and that risk doesn't fall on one person. It falls on the spouse who may be left with substantially fewer assets. It falls on adult children who step in if resources run short. Not everyone has that tolerance, and that's a legitimate answer rather than a failure of nerve.
Insurance Policy. Sharing the risk with an insurance company in exchange for a premium. Instead of pure long-term care insurance, we’ve seen many couples opt for some hybrid combination of life insurance with long-term care benefits built into the policy. We don’t sell insurance products, but can help you plan and coordinate with independent insurance professionals who can help you find a suitable policy.
Using home equity: If you eventually move to assisted living or another care setting, selling the home could unlock significant equity to help fund those costs. You could also potentially access that equity while remaining in the home. The idea isn’t to earmark your house for long-term care today, but to recognize that it’s another meaningful asset available if you ever need it.
Getting a Plan in Place
Retirement planning–broadly–is anticipating what you will need and how to fund it. Few retirement costs can be as high as long-term care. Many families default to procrastinating until they need it.
In our Retirement Game Plan, we believe in setting a course that fits your desires and assets as early as possible so you get the most favorable terms. And once you have a plan in place to fund your long-term care, it brings peace and confidence in the meantime (because you know that's taken care of). You can get back to living and spending more confidently without a big “what-if” looming on the periphery.
So while there is much more to your retirement than long-term care planning, we believe it is an indispensable step in crafting your best Retirement Game Plan.
If you'd like to learn more about how we design your comprehensive retirement plan, including exploring long-term care, you can learn more here.
–––––
The Retirement Game Plan is the planning process we take every client through. If you'd like to talk through what asset location means for your own plan, a good place to start is a complimentary conversation with one of our coaches. You can schedule one at financialcoachgroup.com/contact.
Not intended as a recommendation or offer of any specific advice or services. All investments carry risk, and past performance does not guarantee future results. For detailed information about our fees, services, and background, please view our regulatory disclosure materials on the SEC Investment Adviser Public Disclosure Website (https://adviserinfo.sec.gov/firm/summary/170478).
Stay Informed, Retire Confidently
Join our community of savvy retirees and get our latest insights first
Investment Advice offered through FC Advisory LLC, a registered investment adviser doing business as “New Wealth Project” and as “Financial Coach”. This content is provided for informational purposes only. Views and opinions expressed are those of the authors and do not necessarily reflect those of FC Advisory, LLC. Information provided is not and should not be interpreted as investment, tax, legal, or other professional advice or recommendation by FC Advisory, LLC or the members of our firm. Always consult the appropriate professional regarding your specific situation before implementing any options presented or inferred. FC Advisory LLC, All rights reserved.
Read more

Avoiding Medicare Headaches
Medicare can come with plenty of confusion and a little anxiety.

What To Do After You've Saved More Than You Need For Retirement
The value of planning goes far beyond “making sure you have enough.”
Owen Mulhern
Your First Retired Years, On Diversification & Tax-Smart Giving
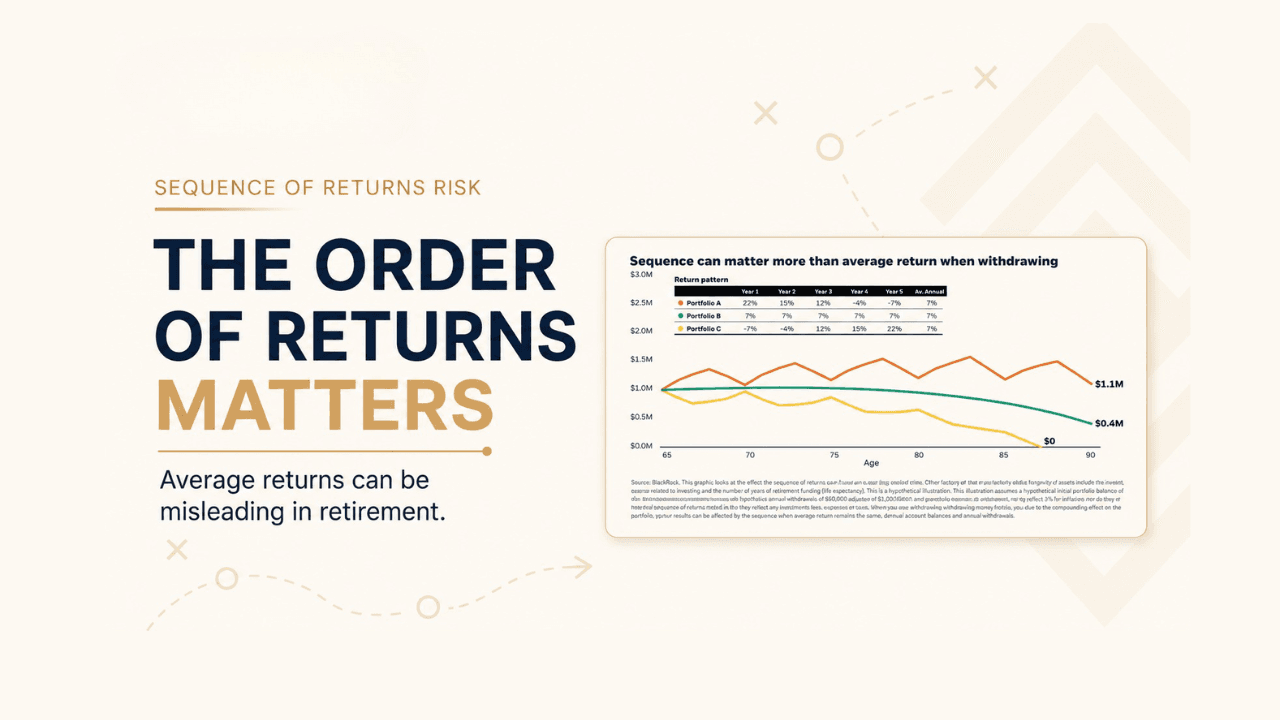
We suggest that many of the families we meet use some sort of calculator to model their portfolio over the span of their retirement.
Owen Mulhern